
radf_common tests for a bubble that is common to a panel of series (Chen,
Phillips & Shi, 2023). It extracts the first principal component of the panel
and runs the ordinary radf test on it. The output is an ordinary
radf_obj, so every downstream method (tidy(), autoplot(),
datestamp() and so on) works on it without further effort.
Arguments
- data
A univariate or multivariate numeric time series object, a numeric vector or matrix, or a data.frame. A column may have leading or trailing
NAvalues, which describes an unbalanced panel in which series enter or exit the sample at different times. Those periods are filled withNAinbadfandbsadfand excluded from theadf,sadfandgsadfof that series. InteriorNAvalues (a gap in the middle of a series) are not supported. When any series is padded in this way, the panel statistics (bsadf_panelandgsadf_panel) are not available, and the function returnsNAfor them with a warning.- minw
A positive integer. The minimum window size (default = \((0.01 + 1.8/\sqrt{T})T\), where T denotes the sample size).
- r
Number of principal components to extract (default 1, which the paper recommends as "sufficient... for the purpose of bubble identification"). Only the first is used for detection. The others are returned for inspection in the
"prcomp"attribute.
Value
A radf_obj (see radf) computed on the first principal
component of the panel, with the fitted prcomp object attached as an
attribute (attr(x, "prcomp")).
Details
Theorem 4.3 of the paper claims that the null limiting distribution of the
resulting statistic is asymptotically identical to the standard PSY/GSADF
distribution, which would let radf_mc_cv apply directly. An
independent validation found that this identity does not hold at
practical panel widths N. At N = 100 the true critical value is
more than double that of radf_mc_cv, and the gap grows as N
increases. PCA on a panel of independent (non-cointegrated) I(1) series does not
behave like a single random walk once there are more series from which
transient co-movement can arise. Use radf_common_cv for the
critical values and not radf_mc_cv. The critical values of
radf_mc_cv do not depend on the panel width, and they are badly
undersized here once N grows past a handful of series.
Note
The function returns the output of radf() computed on the extracted
factor, and radf_common_cv() computes the full time-varying boundary
alongside the scalar critical values. The full summary(),
datestamp, tidy and autoplot pipeline therefore works
(see vignette("naming-and-analysis", package = "exuber")).
References
Chen, Y., Phillips, P. C. B., & Shi, S. (2023). Common Bubble Detection in Large Dimensional Financial Systems. Journal of Financial Econometrics, 21(4), 989-1063.
See also
radf for the underlying test, which is unmodified, and
radf_common_cv for its critical values, which are specific to the
panel width.
Other multivariate:
cobubble_test(),
contagion_reg()
Examples
# \donttest{
# A panel of 5 series driven by one shared latent bubble factor
x <- sim_common(n_series = 5, n = 100, seed = 123)
res <- radf_common(x, minw = 20)
print(res)
#>
#> ── radf (minw = 20, lag = 0) ───────────────────────────────────────────────────
#>
#> id adf sadf gsadf
#> series1 -2.577 5.78 5.922
#>
#> gsadf_panel
#> 5.922
#>
# radf_common_cv() is needed here and radf_mc_cv() does not apply (see Details)
cv <- radf_common_cv(n = 100, N = ncol(x), minw = 20)
summary(res, cv = cv)
#>
#> ── Summary (minw = 20, lag = 0) ────────────────── Monte Carlo (nboot = 1000) ──
#>
#> series1 :
#> # A tibble: 3 × 5
#> stat tstat `90` `95` `99`
#> <fct> <dbl> <dbl> <dbl> <dbl>
#> 1 adf -2.58 0.333 0.676 1.32
#> 2 sadf 5.78 1.86 2.12 2.71
#> 3 gsadf 5.92 2.26 2.55 3.22
#>
# The result is an ordinary radf_obj, so autoplot() and datestamp() work directly
autoplot(res, cv = cv)
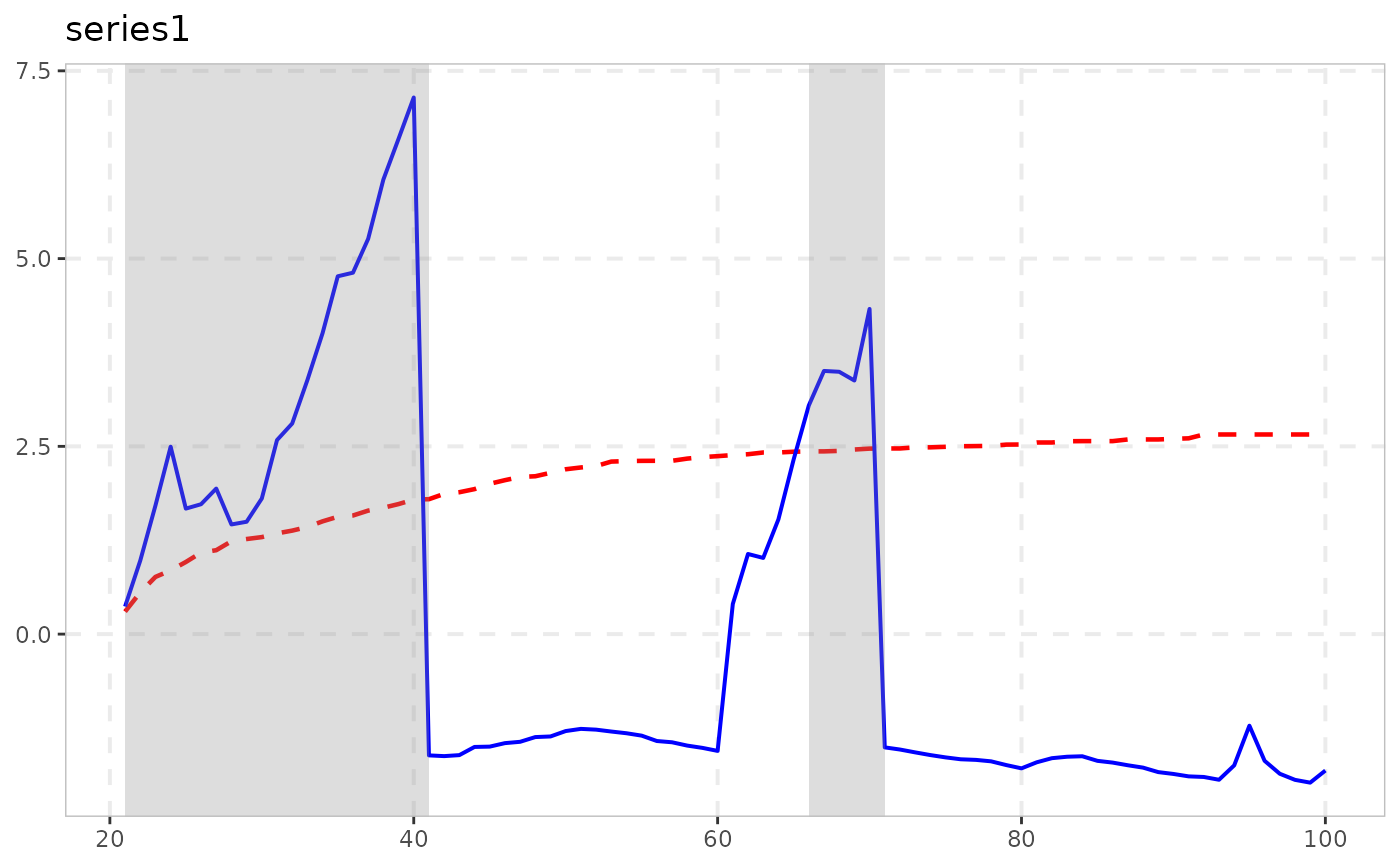 datestamp(res, cv = cv)
#>
#> ── Datestamp (min_duration = 0) ───────────────────────────────── Monte Carlo ──
#>
#> series1 :
#> Start Peak End Duration Signal Ongoing
#> 1 46 55 56 10 positive FALSE
#>
# }