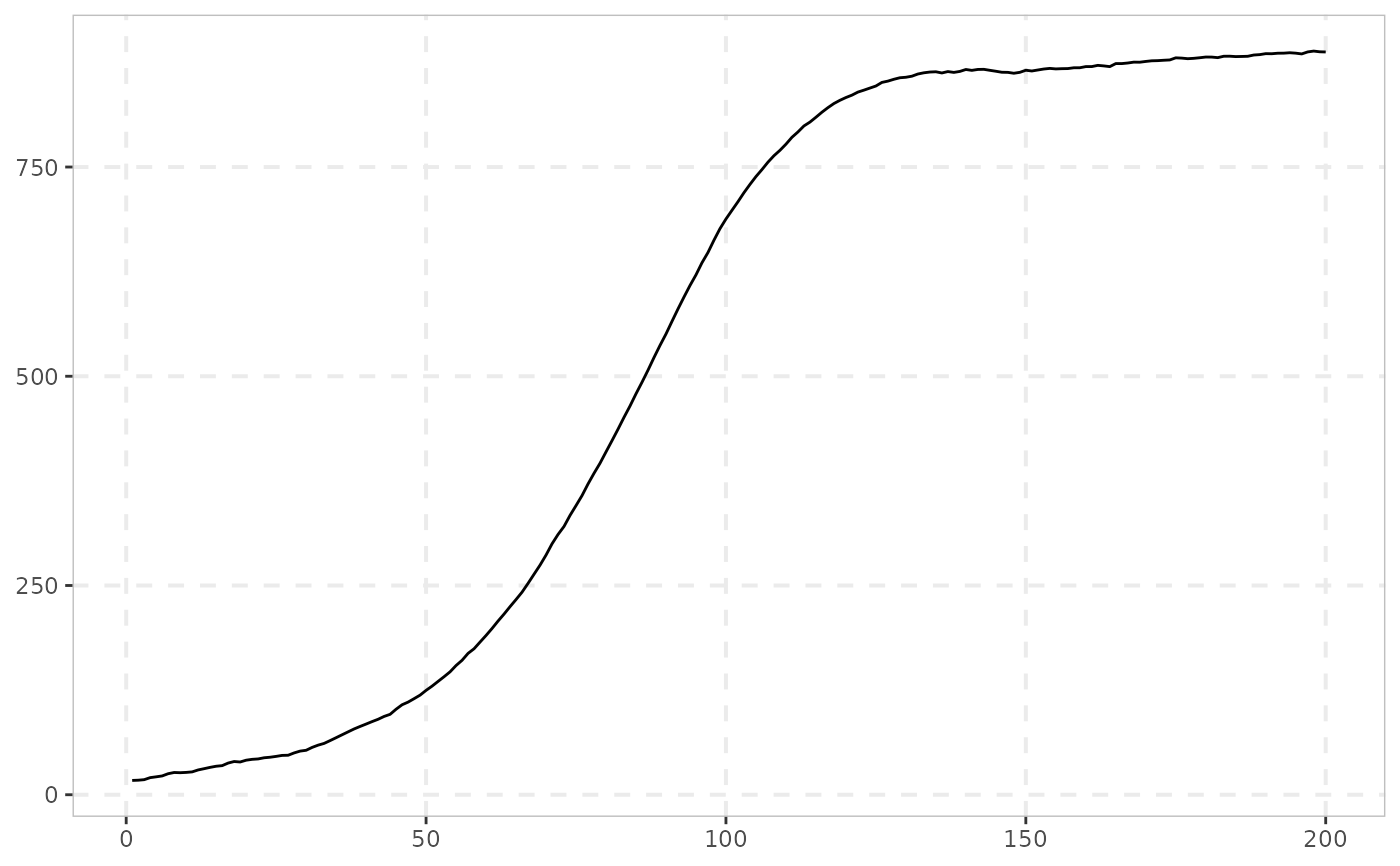
Simulation of a deterministic technology-adoption "false bubble" null
Source:R/sim.R
sim_falsebubble.RdSimulates the false-bubble process of Chen, Chen, Huang, Li & Zhang (2026): a hump-shaped, deterministic technology-adoption shock embedded in dividend growth. It is engineered so that a Campbell-Shiller present-value fundamental alone, with no bubble component at all, displays a price path that looks locally explosive. It is useful as a null (no-bubble) stress test that differs from a plain random walk.
Arguments
- n
A positive integer specifying the length of the simulated output series.
- t1
Adoption (ramp-up start) date, in
1:n.- t2
Maturation (shock end) date, in
t1:n.- kappa
Peak lag (time from
t1to the hump's peak), in0:(t2 - t1).- shape
"triangular"(default) or"gaussian".- amplitude
A positive scalar scaling the hump's peak height.
- mu
A scalar, the baseline dividend-growth drift.
- sigma_d
A positive scalar, the dividend-growth innovation standard deviation.
- r
A positive scalar, the discount rate.
- d0
Starting (log) dividend level.
- seed
An object specifying if and how the random number generator (rng) should be initialized. It is either NULL or an integer, which is passed to
set.seedbefore the simulation. If you set it, the value is saved as the "seed" attribute of the returned value. The default, NULL, leaves the state of the rng unchanged and returns .Random.seed as the "seed" attribute. Results are reproducible across the parallel and the non-parallel option when you use the same seed.
Details
Dividends follow a random walk with drift plus the technology hump:
\(d_t = d_{t-1}+\mu+\tau_t+\eta_t\). The hump \(\tau_t\) either rises linearly from t1 to
t1 + kappa and then falls linearly to t2 (shape =
"triangular", the worked example of the source, eq. 4), or follows a Gaussian
bump centered at t1 + kappa (shape = "gaussian"). Because
\(\tau_t\) is deterministic and known in advance, its contribution to
the price is an exact forward-looking discounted sum,
\(T_t=\sum_{s>t}\beta^{s-t}\tau_s\)
with \(\beta=1/(1+r)\), which is added to the fundamental
pricing formula that sim_div uses. This is a simplified
single-shock reproduction of the mechanism in the source (a deterministic hump
gives a hump-shaped fundamental price and no bubble). It does not include the
full DOLS and multiple-functional-form robustness machinery of the source.