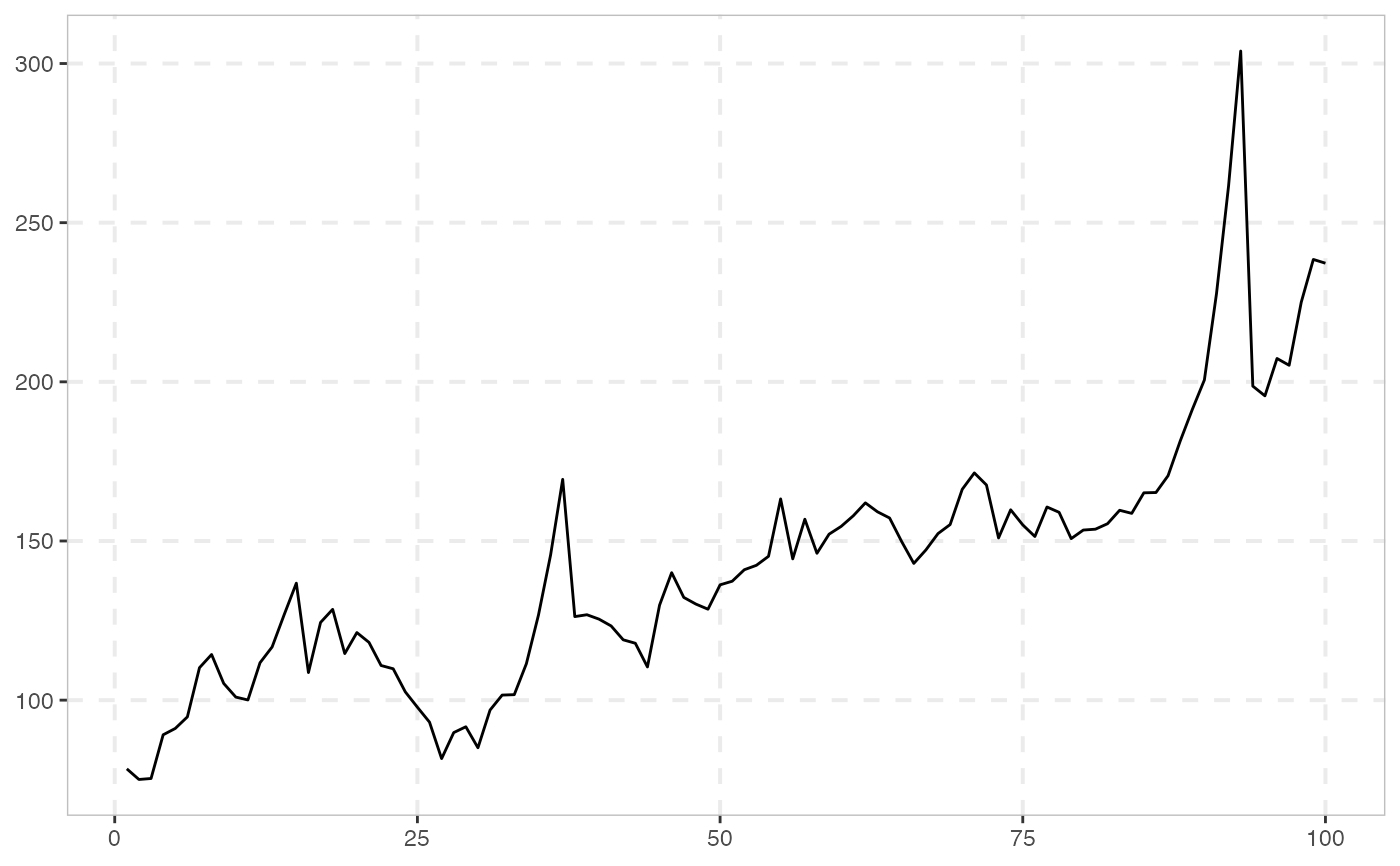
Simulate (log) dividends from a random walk with drift.
Usage
sim_div(
  n,
  mu,
  sigma,
  r = 0.05,
  log = FALSE,
  output = c("pf", "d"),
  seed = NULL
)
Arguments
- n
A positive integer specifying the length of the simulated output series.
- mu
A scalar indicating the drift.
- sigma
A positive scalar indicating the standard deviation of the innovations.
- r
A positive value indicating the discount factor.
- log
Logical. If true dividends follow a lognormal distribution.
- output
A character string giving the fundamental price("pf") or dividend series("d"). Default is
pf.- seed
An object specifying if and how the random number generator (rng) should be initialized. It is either NULL or an integer, which is passed to
set.seedbefore the simulation. If you set it, the value is saved as the "seed" attribute of the returned value. The default, NULL, leaves the state of the rng unchanged and returns .Random.seed as the "seed" attribute. Results are reproducible across the parallel and the non-parallel option when you use the same seed.
Details
If log is set to FALSE (default value) dividends follow:
$$d_t = \mu + d_{t-1} + \epsilon_t$$
where \(\epsilon \sim \mathcal{N}(0, \sigma^2)\). The default parameters are \(\mu = 0.0373\), \(\sigma^2 = 0.1574\) and \(d_0 = 1.3\) (the initial value of the dividend sequence). The above equation can be solved to yield the fundamental price:
$$F_t = \mu(1+r)r^{-2} + r^{-1}d_t$$
If log is set to TRUE then dividends follow a lognormal distribution or log(dividends) follow:
$$\ln(d_t) = \mu + \ln(d_{t-1}) + \epsilon_t$$
where \(\epsilon \sim \mathcal{N}(0, \sigma^2)\). Default parameters are \(\mu = 0.013\), \(\sigma^2 = 0.16\). The fundamental price in this case is:
$$F_t = \frac{1+g}{r-g}d_t$$
where \(1+g=\exp(\mu+\sigma^2/2)\). All default parameter values are those suggested by West (1988).