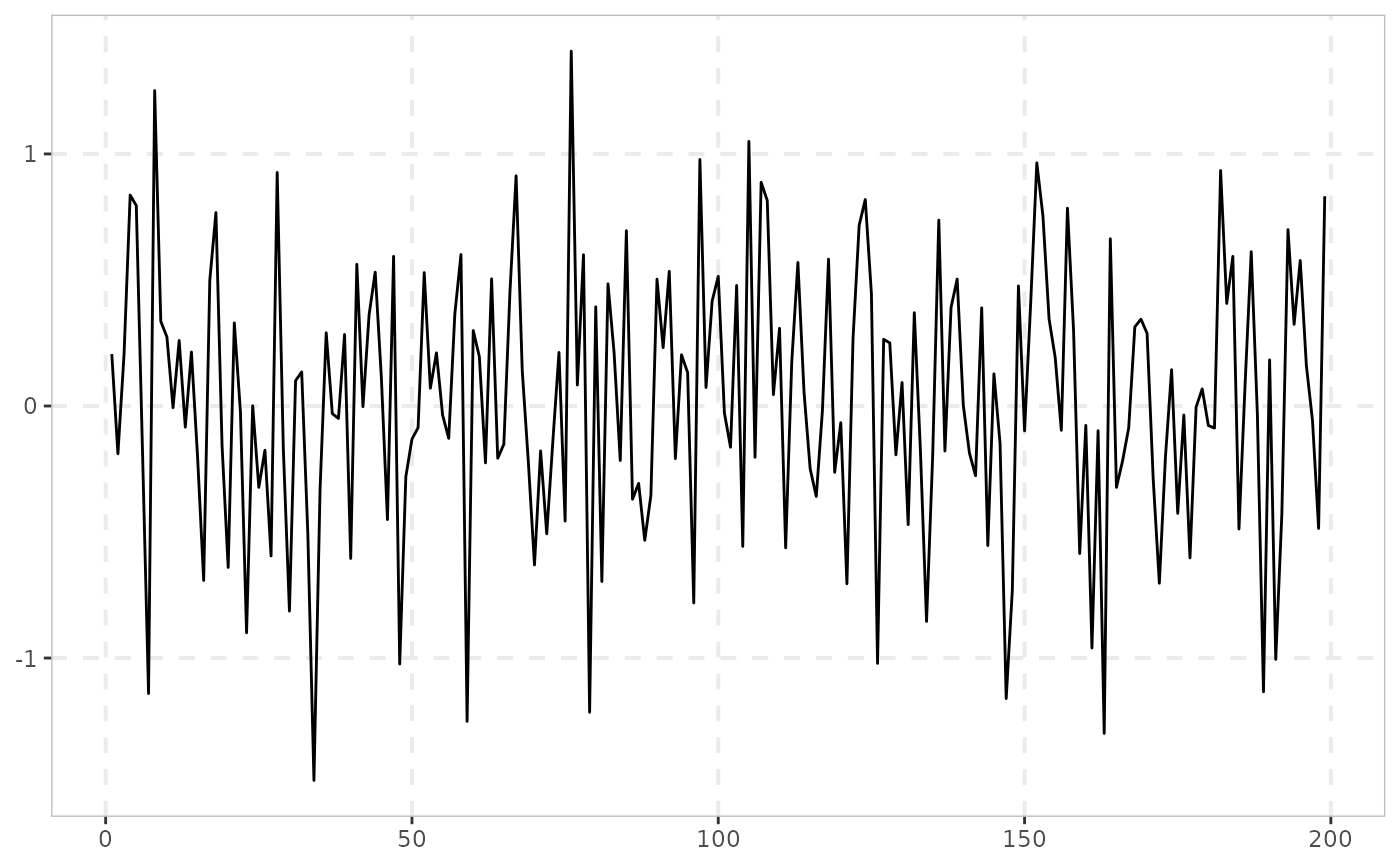
Generates shocks driven by a Cox-Ingersoll-Ross (square-root) stochastic
variance process, discretized with the Euler-Maruyama scheme, for use as
sim_psy1(..., e = sim_vol_cir(...)).
Arguments
- n
Number of innovations to generate.
- kappa, theta, xi
Positive CIR parameters (speed of mean reversion, long-run variance and volatility of volatility).
- sigma0_sq
Non-negative starting variance. Defaults to
theta.- seed
An object specifying if and how the random number generator (rng) should be initialized. It is either NULL or an integer, which is passed to
set.seedbefore the simulation. If you set it, the value is saved as the "seed" attribute of the returned value. The default, NULL, leaves the state of the rng unchanged and returns .Random.seed as the "seed" attribute. Results are reproducible across the parallel and the non-parallel option when you use the same seed.
Details
$$d\sigma^2(r) = \kappa(\theta - \sigma^2(r))dr + \xi\sigma(r)dB(r)$$
discretized over n steps of r in \([0, 1]\). The variance is
reflected at zero if a step would take it negative. The default parameters
(\(\kappa=0.03\), \(\theta=0.25\),
\(\xi=0.1\)) match the robustness design of Harvey, Leybourne & Zu
(2019), which is "representative of Bollerslev and Zhou (2002)".
References
Harvey, D.I., Leybourne, S.J. & Zu, Y. (2019). "Testing explosive bubbles with time-varying volatility." Econometric Reviews, 38(10), 1131-1151.