
dating_hls dates a single bubble episode by fitting four candidate
regime-dummy regressions of Delta y_t on y_{t-1}
(unit-root-to-end, unit-root-bubble-unit-root, unit-root-bubble-collapse and
unit-root-bubble-collapse-unit-root). It fits each by minimizing the residual
sum of squares over candidate break fractions and selects among them by BIC.
Arguments
- data
A univariate or multivariate numeric time series object, a numeric vector or matrix, or a data.frame. A column may have leading or trailing
NAvalues, which describes an unbalanced panel in which series enter or exit the sample at different times. Those periods are filled withNAinbadfandbsadfand excluded from theadf,sadfandgsadfof that series. InteriorNAvalues (a gap in the middle of a series) are not supported. When any series is padded in this way, the panel statistics (bsadf_panelandgsadf_panel) are not available, and the function returnsNAfor them with a warning.- trim
Minimum fraction of the (differenced) sample required in every regime (default 0.05, following the choice of Harvey, Leybourne & Sollis in their empirical application. Their simulations use 0.1).
Value
An object of class dating_hls_obj: a list with the selected model
(model, one of 1:4), its breakpoint date or dates
(origination, collapse and recovery, with NA for the
breakpoints that the selected model does not have), and the BIC value of every
candidate model (bic, which shows how close the selection was).
Details
datestamp uses threshold crossing on the recursive BSADF
statistic, and dating_pdc uses a fixed structure of three or four
regimes with breaks that are estimated sequentially and not jointly. This
function searches for the breakpoints jointly within each of four candidate
regime structures and lets the BIC pick the structure itself. It can therefore
distinguish a bubble that collapses to a new stationary regime (Model 3) from a
bubble that fully reverts to a unit root (Model 4) and from a bubble that is
still ongoing at the end of the sample (Model 1), which the fixed regime count of
dating_pdc cannot. The cost is a joint grid search, in place of the
sequential scan of dating_pdc that finds one break at a time.
Note
This is an SSR/BIC model-selection dating procedure and not a hypothesis test, so it needs no critical values.
The function returns its own class and not radf_obj, so it does not work
with summary(), \link{datestamp} and tidy. It has its own print() and
autoplot() methods instead. print() shows the dating table (model, origination, collapse, recovery). See
vignette("naming-and-analysis", package = "exuber") for which functions fit
the shared pipeline and which do not.
References
Harvey, D. I., Leybourne, S. J., & Sollis, R. (2017). Improving the accuracy of asset price bubble start and end date estimators. Journal of Empirical Finance, 40, 121-138.
See also
dating_pdc for the cheaper sequential-splitting
alternative that this function complements, and datestamp for the
original threshold-crossing rule of PSY.
Other dating:
dating_hlw(),
dating_knp(),
dating_pdc(),
radf_recovery(),
rootstamp()
Examples
# \donttest{
res <- dating_hls(sim_data$psy1, trim = 0.05)
print(res)
#>
#> ── dating_hls (n = 100, trim = 0.05) ───────────────────────────────────────────
#>
#> series model origination collapse recovery
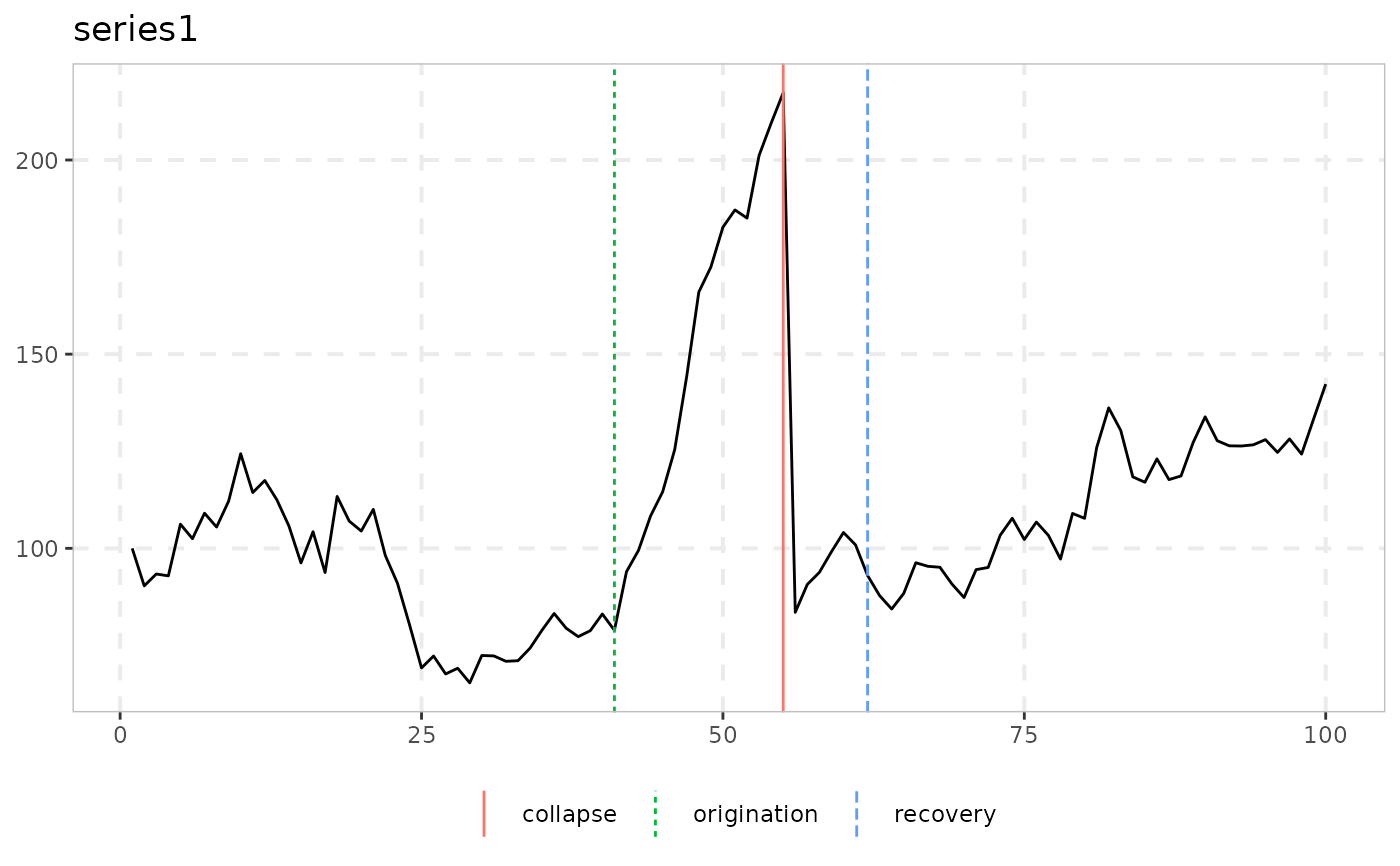
#> series1 4 41 55 62
#>
# Plot the series with the selected model's breakpoint(s) overlaid
autoplot(res)
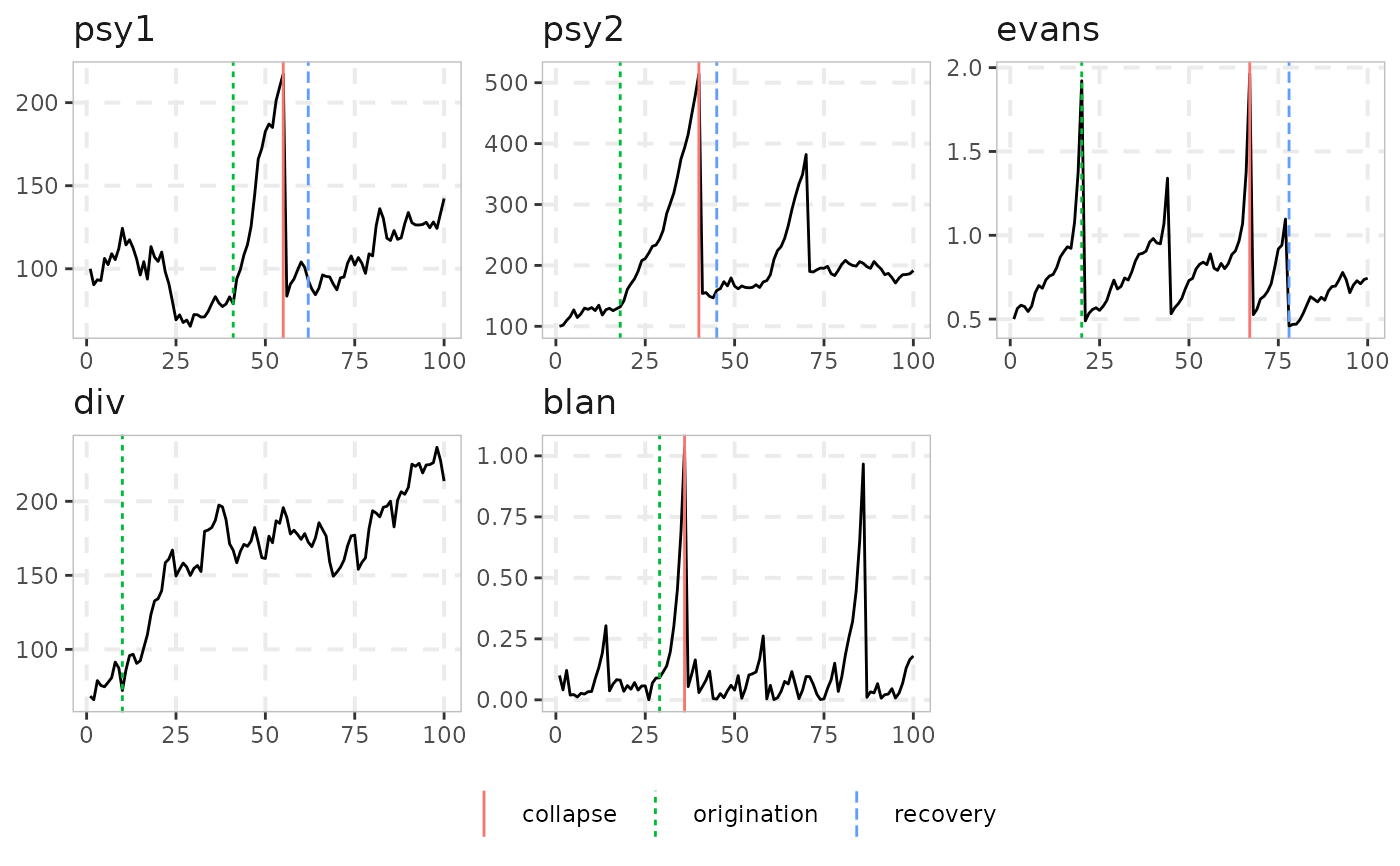
 # A whole panel at once, with one subplot for each series
autoplot(dating_hls(sim_data, trim = 0.05))
 # }