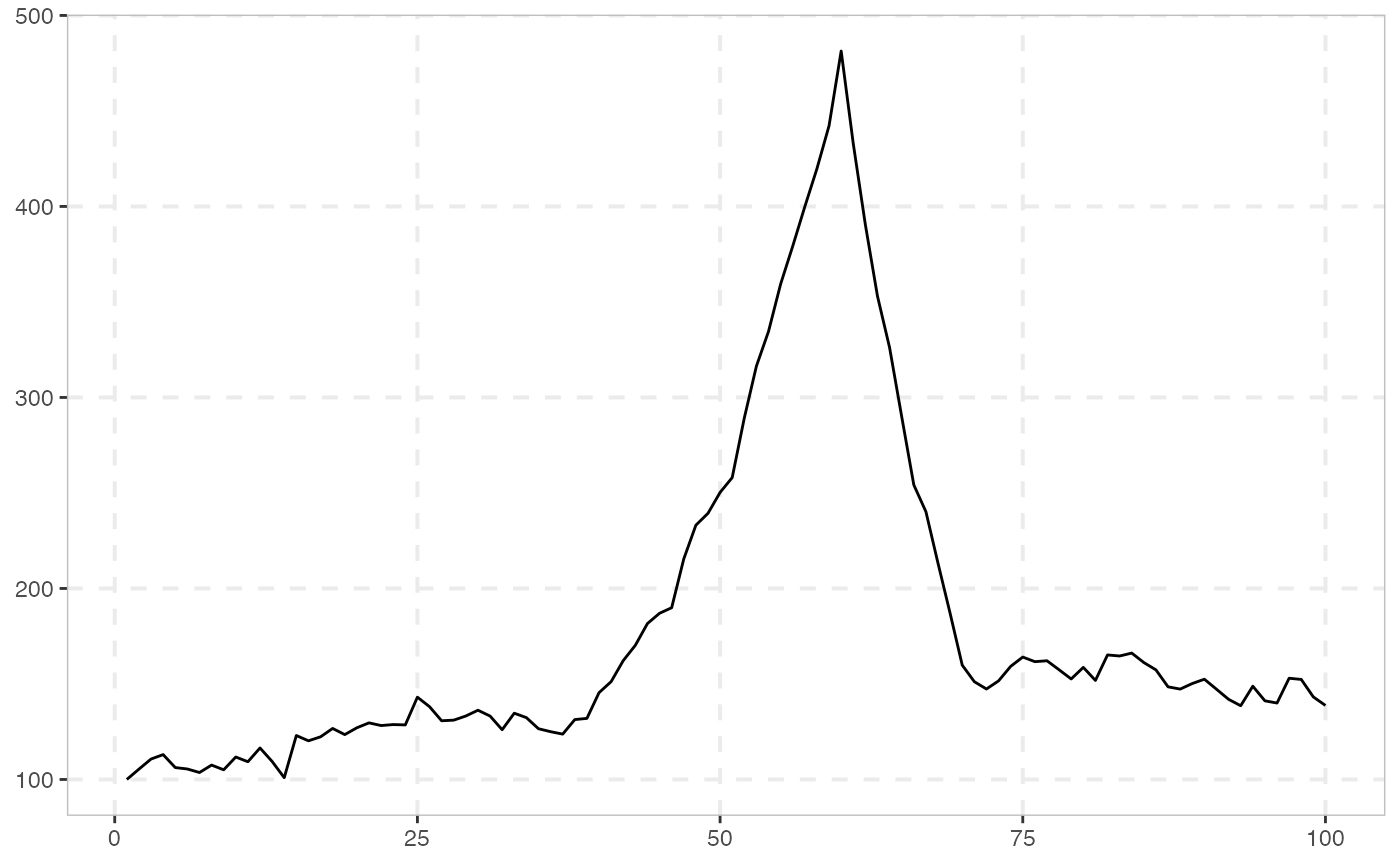
Simulation of a single-bubble process with multiple forms of collapse regime
Source:R/sim.R
sim_ps1.RdThe process differs from the sim_psy1 model in three respects (Phillips and
Shi 2018). First, it includes an asymptotically negligible drift in the martingale
path during normal periods. Second, the collapse is modeled directly as a
transient mildly integrated process that covers an explicit period of market
collapse. Third, it introduces a market recovery date to capture the return to
normal market behavior. Three forms of collapse are available:
sudden:withbeta = 0.1andtr = tf + 0.01*ndisturbing:withbeta = 0.5andtr = tf + 0.1*nsmooth:withbeta = 0.9andtr = tf + 0.2*n
To set the duration of the collapse period through tr = tf + 0.2n, you must
also provide tf.
Usage
sim_ps1(
  n,
  te = 0.4 * n,
  tf = te + 0.2 * n,
  tr = tf + 0.1 * n,
  c = 1,
  c1 = 1,
  c2 = 1,
  eta = 0.6,
  alpha = 0.6,
  beta = 0.5,
  sigma = 6.79,
  seed = NULL,
  e = NULL
)
Arguments
- n
A positive integer specifying the length of the simulated output series.
- te
A scalar in (0, tf) specifying the observation in which the bubble originates.
- tf
A scalar in (te, n) specifying the observation in which the bubble collapses.
- tr
A scalar in (tf, n) specifying the observation in which market recovers
- c
A positive scalar determining the drift in the normal market periods.
- c1
A positive scalar determining the autoregressive coefficient in the explosive regime.
- c2
A positive scalar determining the autoregressive coefficient in the collapse regime.
- eta
A positive scalar (>0.5) determining the drift in the normal market periods.
- alpha
A positive scalar in (0, 1) determining the autoregressive coefficient in the bubble period.
- beta
A positive scalar in (0, 1) determining the autoregressive coefficient in the collapse period.
- sigma
A positive scalar indicating the standard deviation of the innovations.
- seed
An object specifying if and how the random number generator (rng) should be initialized. It is either NULL or an integer, which is passed to
set.seedbefore the simulation. If you set it, the value is saved as the "seed" attribute of the returned value. The default, NULL, leaves the state of the rng unchanged and returns .Random.seed as the "seed" attribute. Results are reproducible across the parallel and the non-parallel option when you use the same seed.- e
An optional numeric vector of length
n - 1with innovations to use in place ofrnorm(n - 1, sd = sigma). It lets the plain PSY equation above be driven by a shock sequence that is non-Gaussian, heteroskedastic or dependent instead of i.i.d. Gaussian noise. The generatorssim_innov(heavy-tailed or skewed),sim_vol_break(permanent volatility break),sim_vol_garch(GARCH/TGARCH),sim_vol_cirandsim_vol_sv(stochastic volatility) andsim_fi(long memory) produce suitable sequences. The defaultNULLreproduces the plain i.i.d. Gaussian process exactly.
References
Phillips, Peter CB, and Shu-Ping Shi. "Financial bubble implosion and reverse regression." Econometric Theory 34.4 (2018): 705-753.